When HMRC decides your "Outside IR35" contractor should have been treated as a deemed employee under the off-payroll rules (Chapter 10 ITEPA 2003), you pay the missing tax and interest. HMRC then considers whether you took reasonable care, and if you did not, it will conclude you were careless and add further penalties. The penalties are likely to exceed the final tax bill, at least doubling your exposure.
Tax tribunals have tested the meaning of reasonable care over many years. Our guide, IR35 & Off-payroll - Are you taking Reasonable Care?, lists the scenarios that meet the standard and those that fail it.
If your firm ignores the IR35 and off-payroll rules, HMRC will almost certainly find you careless. You then face the harsh penalties, and HMRC can reach back six years instead of four.
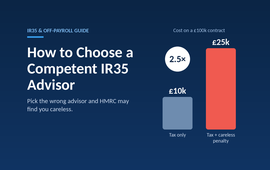
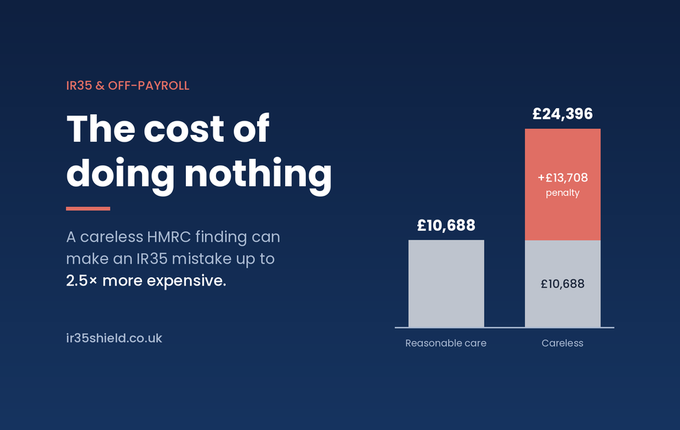
WARNING: A careless HMRC finding can make an IR35 mistake up to 2.5 times more expensive for your firm.
How much does a careless finding add to your IR35 bill?
Consider a single contractor engagement for £100,000 that your firm treated as outside IR35 (paid gross) without making a status determination. HMRC investigates and concludes that it was a deemed employment, so you now owe the PAYE income tax and National Insurance that should have been paid.
|
Step |
Amount |
|
Full tax bill on the engagement |
£45,693 |
|
Less: offset for tax the contractor and their company already paid |
(£31,442) |
|
Less: Corporation Overpayment relief on the tax owed |
(£3,563) |
|
Extra tax the firm actually pays* |
£10,688 |
HMRC credits the tax your contractor and their company already paid. Corporation Tax Overpayment relief then brings the bill down further, and if you took reasonable care, your extra cost stops at £10,688. There will also be some interest to pay (not included above), depending on how many years ago the errors were made, which would apply in all instances.
If HMRC finds you careless, it can charge a careless penalty of up to 30%. It calculates that penalty on the full £45,693 before any offset. Your penalty comes to £13,708, and the total bill climbs to £24,396 before interest.
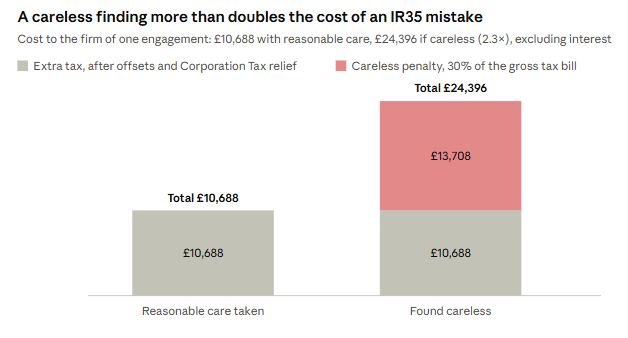
Penalties attract no Corporation Tax Overpayment relief, so the whole £13,708 comes straight off your net profit.
How to get IR35 compliance right
The good news is that getting IR35 compliance right and not incurring penalties is straightforward. Meeting the standard for reasonable care means taking a prudent approach and, where needed, relying on competent advisors and acting on their advice.
A competent IR35 advisor will be registered with HMRC as a tax advisor, and work under signed terms with professional indemnity cover, typically up to £1,000,000. They will know the IR35 statute and case law, and will have handled HMRC status enquiries and tribunal cases. They can also give you formal written opinions.
You can protect your firm with five simple steps:
- Use expert-reviewed contracts: Have an IR35 specialist check your written contracts.
- Make robust status determinations: Assess every engagement before it starts.
- Train your staff: Ensure hiring managers apply the rules correctly.
- Document your IR35 processes: Put them in writing and keep the evidence.
- Call in specialists for HMRC checks: Bring IR35 experts when HMRC opens a compliance check.
HMRC typically treats firms that follow these steps as "low risk", so its compliance checks tend to be quick and straightforward.
Why choose IR35 Shield
IR35 Shield is a specialist advisory that works solely on IR35 and off-payroll working. Hundreds of firms rely on us to meet every hallmark of a competent advisor.
- Front-line experience. We have assisted with many HMRC status enquiries and tax tribunals.
- Proven results. We have closed HMRC compliance checks under IR35 & off-payroll rules.
- Specialist-led technology. We launched the first online IR35 status test in 2009.
- Unlimited support. Every assessment includes software support and account management.
- Underwritten protection. Markel underwrites us, and we also offer tax investigation services.
Next steps
Every month you leave IR35 unmanaged adds to a six-year exposure that HMRC can penalise at up to 30%. Book a call with our experts and put a process in place that will stand up to an HMRC enquiry.
*Technical footnote: The £100K engagement above was challenged under the off-payroll rules. Payments to the contractor's limited company resulted in full corporation tax and dividend taxes being paid. The employer's NICs are fully payable and cannot be offset by the taxes the contractor paid. Interest is excluded and will apply based on the time period the original purported error was made.